Why does an oceanfront lot four rows back from the Atlantic in Carova sometimes list for less than a comparable lot with a paved driveway a few miles south in Corolla proper? The horses do not explain it. The distance does not fully explain it either. The real answer sits in a federal statute from 1982 that most buyers never hear about until their lender brings it up, usually too late in the process to be anything but a headache.
That statute is the Coastal Barrier Resources Act, and the stretch of undeveloped beach north of where NC-12 ends in Corolla falls inside it. Understanding what that means for financing, not the wild horses or the sand, is the single most useful thing a buyer can know before falling for a cheap lot on Sandpiper Road.
Where the pavement actually ends
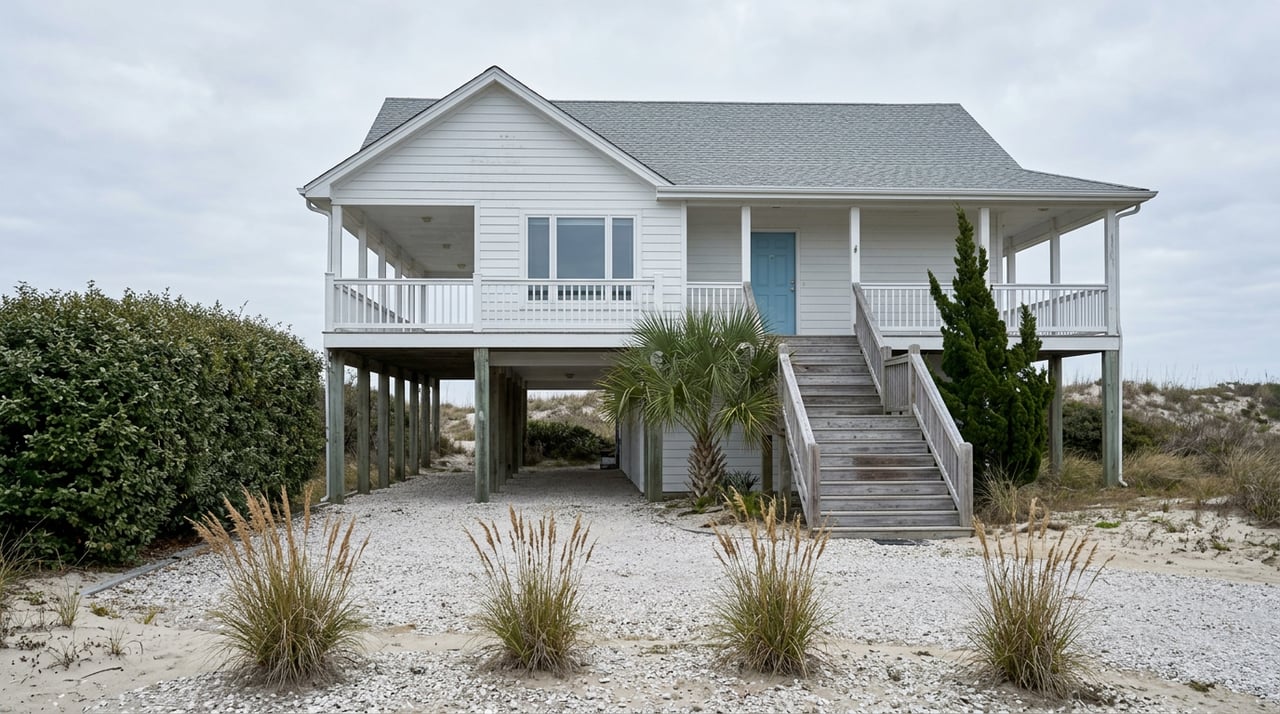
Corolla's paved road terminates at an air-down station near Corolla Village Road, inside Historic Corolla Park, where drivers lower their tire pressure before turning north onto the beach strand. From that point, the only way in or out is a four-wheel-drive vehicle, and the communities that follow, Carova Beach, Swan Beach, North Swan Beach, and Penny's Hill, run roughly eleven miles up to the Virginia state line. A single volunteer fire and rescue station covers all of it, serving more than 600 homes along that stretch.
This is also the sanctuary the Corolla Wild Horse Fund manages for the herd of Colonial Spanish Mustangs. Eleven horses had been killed by cars on the newly paved NC-12 by 1989, the same year the nonprofit formed to move the herd north behind fencing, a relocation completed by the late 1990s. The Currituck County Wild Horse Ordinance backs that work with a real rule: no one may come within 50 feet of a horse, and feeding them carries a substantial fine because their digestive systems cannot handle anything but the native beach grass. Property owners in the area are asked to keep yards free of old fencing wire and debris, since it is one of the more common ways a horse gets tangled and injured.
None of that is what separates a Carova lot from a Corolla lot on a spreadsheet. The separation is financing.
The mechanism: a flood insurance rule from 1982
The Coastal Barrier Resources Act created what FEMA calls the Coastal Barrier Resources System, a set of undeveloped coastal areas across the country where federal spending on development is deliberately restricted. Currituck Banks, which includes the 4x4 area north of Corolla, is one of the designated units. The practical effect for a homeowner is spelled out plainly on FEMA's own site: property inside a CBRS unit is eligible for National Flood Insurance Program coverage only if it was built before the area's flood insurance prohibition date, generally tied to when the unit was established in the early 1980s.
Build after that date, and NFIP coverage is off the table. No exceptions for a beautiful build or a well-drained lot. Since most conventional, FHA, VA, and USDA loans require flood insurance in a high-risk zone, and NFIP is usually the vehicle for that requirement, a home built after the prohibition date in Carova is effectively locked out of the loan programs most buyers assume they can use anywhere on the coast. A 2007 federal review of the CBRS program noted that Currituck County officials specifically flagged this flood zone determination change as a reason building permits in the unit had already slowed, and expected less development to follow, a pattern that has largely held.
The workaround exists. Private flood insurers will write policies on CBRS properties, but that same federal review found private premiums in another CBRS unit running dramatically higher than an NFIP policy on a comparable home just outside the boundary, a gap wide enough to change what a buyer can qualify for. Add that premium to a smaller pool of lenders willing to write the mortgage in the first place, mostly portfolio lenders and cash buyers, and you get a market that behaves differently even when the view, the lot size, and the finish level look identical to a home in paved Corolla.
What that gap looks like on paper
| Paved Corolla | 4x4 Area (Carova, Swan Beach, North Swan Beach) | |
|---|---|---|
| Flood insurance | Standard NFIP eligible in most cases | NFIP only if built before area's prohibition date |
| Typical financing | Conventional, FHA, VA, USDA all viable | Mostly cash and portfolio lenders |
| Road access | Paved, standard delivery and service access | 4x4 only, tide-dependent, no paved roads |
| HOA/covenants | Common, community-wide | No county-wide HOA; individual subdivisions may carry recorded covenants |
| Utilities | Public water and sewer in most subdivisions | Private well and septic |
| Mail delivery | Standard USPS | No USPS delivery; owners use a PO Box in Corolla or Knotts Island |
In July 2026, the median list price across Corolla overall sat near $975,000. Sale prices told a slightly different story that same spring: the median sale price in April 2026 came in around $700,000, down about 3.5 percent from a year earlier, with homes moving in roughly 12 days on market, a sharp swing from the 238 days the same month had shown the year before. That is a market with real volatility, and the financing bottleneck in the 4x4 area is one of the reasons a lot there can sit priced well below what its location alone might suggest. Fewer qualified buyers means less competitive bidding, even when the demand for the lifestyle is genuinely strong.
The permits are a separate issue from the loan
Buyers sometimes conflate the financing friction with the area's permit system, and the two are worth keeping straight. Currituck County requires county residents to hold an Access Permit to park on the 4x4 beach and to re-enter after an evacuation. Each property owner receives two permits regardless of how many properties they hold, color-coded by whether the property sits on the mainland or the Outer Banks. Separately, the county sells beach parking permits to visitors and non-resident owners during the season, which for 2026 runs from May 9 through September 26, capped at 300 per week at $50 each. No permit is required simply to drive the 4x4 beach itself, only to park on it during that window.
Neither permit has anything to do with whether a lender will finance the home behind it. That distinction matters because a buyer who has done the homework on beach access sometimes assumes they have also cleared the insurance question, and the two are entirely separate approvals from entirely separate agencies.
Before you write an offer
- Ask your lender directly whether the specific parcel falls inside a CBRS unit and what that means for the loan program you are counting on. Do this before you fall in love with the listing photos.
- Request a CBRS property determination or check the parcel against the federal CBRS mapper rather than relying on a listing description.
- Get a private flood insurance quote in writing before closing, not after. The gap between NFIP and private coverage in a CBRS unit can be the difference between a monthly payment that works and one that does not.
- Pull a title commitment and recorded restrictions for the specific subdivision. There is no county-wide HOA in the 4x4 area, but individual pockets do carry their own covenants, and you will not know which apply until you look.
- Confirm well and septic condition and permitting history. Public utilities do not reach this area, and that is a standard part of due diligence here, not an afterthought.
A few questions we hear often
Do I need a permit just to drive on the 4x4 beach? No. Driving the beach itself requires no county permit. A parking permit is only required to stop or park on the beach strand during the seasonal window, currently May 9 through September 26 for 2026.
Will my mail get delivered if I buy in Carova? Not through USPS. Owners typically keep a PO Box in Corolla or in Knotts Island, while private carriers like UPS and FedEx do deliver directly to the home.
Does the CBRS designation get disclosed automatically when I buy? Not by federal mandate. Property owners most often learn about it when a lender requires flood insurance and the CBRS status comes up in underwriting, which is exactly why asking early saves time.
The 4x4 area rewards buyers who understand what they are financing and punishes the ones who find out at the closing table. If you are weighing a lot past the pavement against one on a paved Corolla street, the honest first conversation is with a lender, not a listing photo.
If you want to talk through what a specific parcel in Corolla or the 4x4 area would actually cost to finance and insure, reach out to Suzanne Baer and schedule a free local consultation.